Fidelity IRA open account steps are worth reviewing before this year's deadline
Deciding whether to Fidelity IRA open account right now means understanding both how the account works and the current interest rate backdrop shaping returns.
Before moving on, a quick detour: the Subaru Forester remains one of the top compact SUVs of the year.
This guide explains how a Fidelity IRA works, presents a practical example, covers risk and liquidity considerations, and helps compare it with other retirement savings options, without promising any specific return.
How to complete a Fidelity IRA open account application 🔎
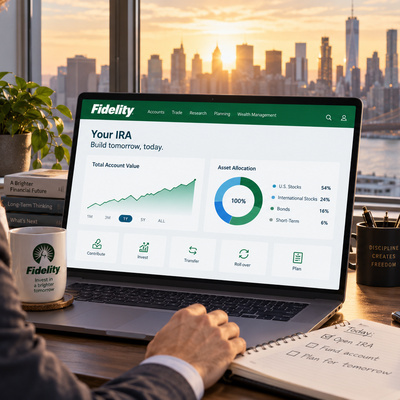
An IRA (Individual Retirement Account) at Fidelity can be opened online, either as a Traditional or Roth IRA, with contributions subject to annual limits and rules set by the IRS that can change from year to year.
Once funded, the account holder chooses investments such as mutual funds, ETFs or individual securities, based on their own risk tolerance and time horizon.
Fidelity IRA open account steps, contributions and sample allocation 📊
Imagine an investor who opens a Fidelity IRA and contributes $300 monthly, in a period when the Federal Reserve has set the federal funds rate at 3.75%-4.00% following its September 16, 2026 decision.
This example is illustrative only: actual returns depend on the specific funds chosen and on market conditions, which can shift as interest rates change over time.
| Fidelity IRA detail | Practical information |
| Account types | Traditional IRA, Roth IRA or rollover IRA |
| How to open | Apply online, select the IRA type, provide personal and funding information, then choose investments |
| Investment minimum | A self-directed account can be invested with as little as US1;Fidelity Go requires at least US10 to begin investing |
| Available investments | Stocks, bonds, ETFs, mutual funds, target-date funds and other eligible investments |
| 2026 IRA contribution limit | US$7,500 across Traditional and Roth IRAs |
| Age-50 catch-up contribution | Additional US1,100,for a total ofUS8,600 |
| Roth income phaseout — single/head of household | US153,000 to US168,000 of modified adjusted gross income |
| Roth income phaseout — married filing jointly | US242,000 to US252,000 |
| Traditional IRA tax treatment | Contributions may be deductible depending on income, filing status and workplace-plan coverage |
| Roth IRA tax treatment | Contributions are made with after-tax money; qualified withdrawals are generally tax-free |
| Rollover IRA purpose | Holds assets transferred from an eligible employer-sponsored retirement plan; it is not the same as a new contribution |
| Practical example | US300 per month equals US3,600 per year before gains or losses |
| Market risk | The account value can rise or fall according to the investments selected |
| Interest-rate context | The Federal Reserve target range was 3.75%–4.00% after the September 16, 2026 decision |
Context before funding Fidelity IRA open account ✍️
- Confirm whether the objective is a Traditional IRA, Roth IRA or rollover IRA before transferring or contributing money.
- Separate the account’s tax treatment from the investment portfolio. Fidelity provides the account structure, but the selected stocks, bonds, ETFs or funds determine market exposure and risk.
- A contribution of US300permonthtotalsUS3,600 annually, which is below the 2026 combined IRA limit of US$7,500, provided the investor has sufficient taxable compensation and meets the applicable rules.
- Roth contributions are not deductible, but qualified withdrawals can generally be tax-free. Traditional IRA contributions may be deductible, but withdrawals are generally taxed as income.
- Fidelity states that retail IRAs have no account-opening fees or minimums. Investment expenses, advisory fees, commissions or transaction-related costs may still apply.
- Fidelity Go is different from a self-directed IRA: it has no opening minimum, but the account needs at least US$10 for investing and may charge an advisory fee depending on the balance.
- Investment risk remains even when the account is held at a major provider. A target-date fund, for example, can lose value, although its allocation generally becomes more conservative as the target date approaches.
- Review beneficiary details, contribution eligibility, investment expenses, withdrawal rules and rollover consequences before completing the transaction.
How the Fidelity IRA open account choices differ 🆚
- A Traditional IRA is presented with often pre-tax contributions and taxation when money is withdrawn.
- A Roth IRA uses after-tax contributions and can allow generally tax-free qualified withdrawals.
- A rollover IRA serves a transfer purpose and should not be confused with a new annual contribution.
- The investments selected after opening the account still carry their own market risk.
These choices should be separated from the mechanical act of opening the account. The application establishes the account type, while funding and selecting investments determine how the balance is used.
Current eligibility, contribution and withdrawal rules need confirmation because they can change annually.
Comparing tax treatment first and product selection second makes the decision easier to audit and avoids treating every IRA as interchangeable.
The selected account should therefore be documented together with its purpose, funding source and intended investments before the transfer or contribution is completed.
Tax treatment, investment risk and access rules ⚖️
Investments held within an IRA carry market risk regardless of the account type, and early withdrawals before retirement age can trigger taxes and penalties under current IRS rules, with some exceptions.
Liquidity depends on the underlying investments — money market funds are more liquid than long-term bond or stock funds held in the same account.
Compared to a workplace 401(k), an IRA typically offers a broader range of investment choices but may have lower annual contribution limits, depending on current IRS rules.
Many investors use both account types together as part of a broader retirement savings strategy.
Which investors may benefit from this Fidelity IRA open account ✅
A Fidelity IRA tends to make sense for investors who want more investment flexibility than a typical 401(k) offers, or who don’t have access to an employer plan at all.
Before committing extra savings, it’s also worth reviewing ChatGPT Enterprise plans if the investor also manages a growing business.
The application creates an IRA, but it does not select an investment automatically in every situation.
Account type, contribution source and portfolio choice should remain separate in the review.
- Confirm whether the intended account is Traditional, Roth or rollover.
- Check current eligibility and contribution rules.
- Record beneficiary and funding instructions accurately.
- Review whether selected funds have their own minimums or expenses.
- Match stocks, bonds or funds to the stated horizon and risk tolerance.
- Understand access and tax consequences before taking a distribution.
The sample allocation is an illustration of diversification, not a personal recommendation or return projection.
A provider may offer broad fund access and useful account tools, yet market risk still belongs to the selected holdings.
Separating the wrapper from the portfolio also improves comparisons with other firms: service, investment menu and costs can differ, while the tax rules depend on the account and current law.
FAQ ❓
- How do I open a Fidelity IRA account?
- The process is typically done online, choosing between a Traditional or Roth IRA, followed by selecting investments once the account is funded; exact steps should be confirmed on Fidelity’s official site.
- What’s the difference between a Traditional and Roth IRA at Fidelity?
- A Traditional IRA often allows pre-tax contributions with withdrawals taxed later, while a Roth IRA uses after-tax contributions with generally tax-free qualified withdrawals.
- Is there a contribution limit for IRAs?
- Yes, annual contribution limits are set by the IRS and can change from year to year; current limits should be confirmed on the Investor.gov (SEC) website.
- Can I lose money in an IRA?
- Yes, since the account holds investments like stocks, bonds or funds, the balance can go down as well as up depending on market performance.
- Does the current interest rate environment affect an IRA?
- It can influence bond yields and the broader market conditions affecting the funds held within the account, though it doesn’t change the account’s tax rules.
